Life Doesn't Come With Instructions.
BUT SOMEBODY HAS PROBABLY ALREADY FIGURED OUT WHAT YOU'RE TRYING TO FIGURE OUT.
StoryClip Media makes everyday knowledge simple, practical, and useful.
What Are You Trying to Figure Out?
You don't need another guru. You just need a clear answer.
Tech • Home • Money • Work • Life • Faith
TECHNOLOGY
Wi-Fi, computers, software, cybersecurity, smart homes and everyday tech.
HOME
Practical help for homeowners, renters, maintenance, projects and everyday home life.
Money
Budgeting, credit, homeownership and everyday financial decisions.
Work
Technology, productivity, career skills and getting more done.
Life Skills
The useful stuff nobody really teaches you how to do.
Faith
Practical guidance for growing your faith and living it out in everyday life.
Featured Resources
Simple answers to questions you are probably asking yourself.
How Can I Use My Home Equity?
If you’ve owned your home for a while, there’s a good chance you’ve built up some equity.
Maybe your home has increased in value. Maybe you’ve paid down a good chunk of your mortgage. Or maybe both have happened.
So naturally, you might be wondering:
How can I actually use that equity?
The short answer is that you may be able to borrow against a portion of your home’s equity through a HELOC, home equity loan, or cash-out refinance.
But before we get into how those work, there’s a more important question:
What are you trying to accomplish with the money?
Because just because you can access your equity doesn’t necessarily mean you should.
Let’s break it down.
What Is Home Equity?
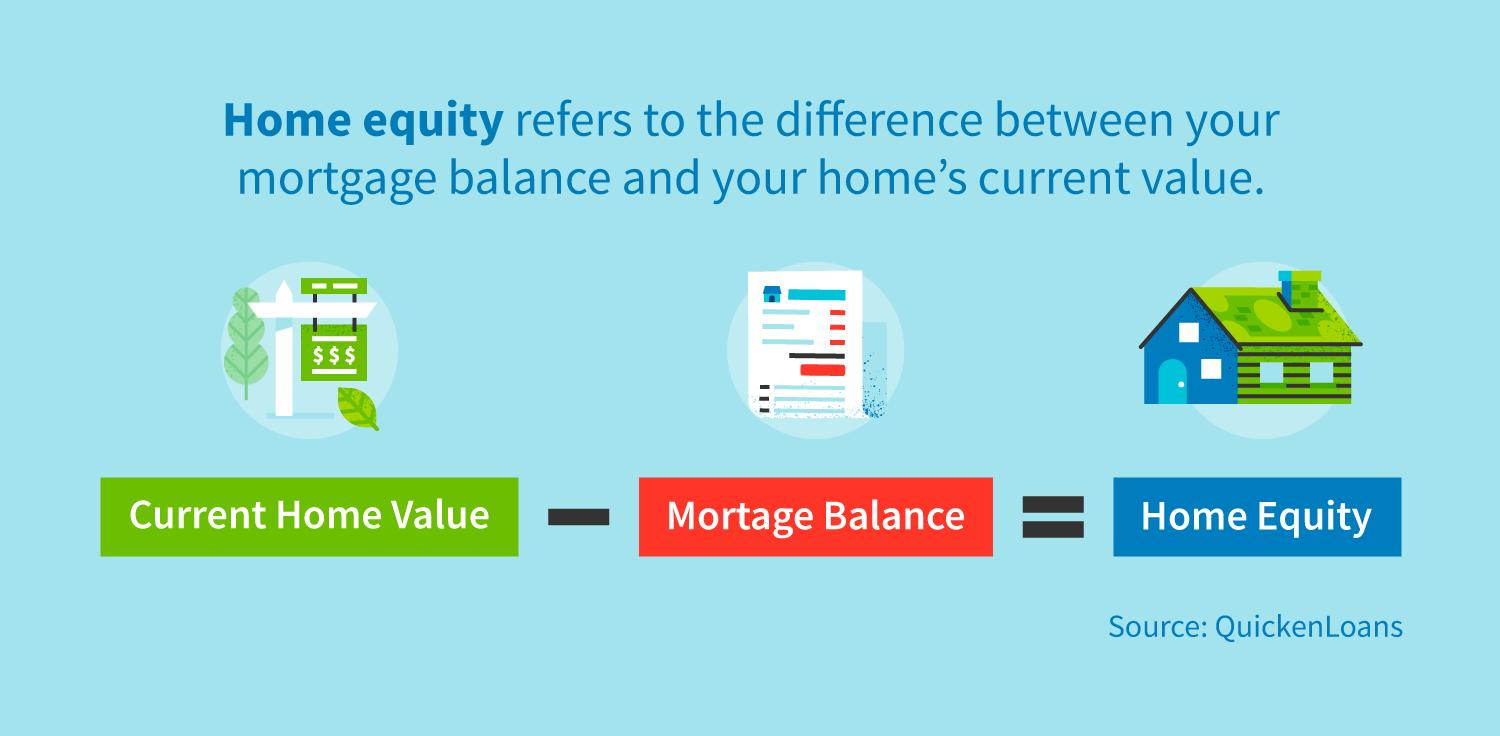
Home equity is basically the difference between what your home is worth and what you still owe against it.
For example:
Let’s say your home is worth $800,000 and you owe $500,000 on your mortgage.
You would have roughly $300,000 in home equity.
That doesn’t necessarily mean you can borrow the entire $300,000. How much you can access depends on things like your home’s value, existing mortgage balance, credit, income, loan program, and lender guidelines.
But that equity is an asset you've built through homeownership—and there are ways to access a portion of it without selling your house.
What Can I Use My Home Equity For?
Technically, home equity can be used for a lot of different things.
The better question is whether using it actually improves your situation.
Here are some of the more common reasons homeowners consider it.
Home Improvements
This is probably one of the most straightforward uses.
Maybe you need another bedroom.
Maybe the kitchen needs to be remodeled.
Maybe you want to build an ADU.
Or maybe there’s a major repair you've been putting off.
Using equity can make sense when you're putting money back into the property, especially when the project improves your family's day-to-day life or potentially adds value to the home.
That doesn't mean spending $50,000 automatically increases your home's value by $50,000.
But if you're planning to stay in the house and the project makes the home work significantly better for you, it's worth looking at the numbers.
Paying Off High-Interest Debt
Let's say you have credit cards charging 20%+ interest.
If you can access your home equity at a substantially lower interest rate, consolidating that debt could potentially lower your interest costs or monthly payments.
But there's an important distinction here.
You're taking debt that may currently be unsecured and replacing it with debt that's attached to your home.
So I wouldn't just ask:
“Can I lower my monthly payment?”
I'd ask:
“Does this actually help me get out of debt?”
If you pay off the credit cards and then immediately start building those balances again, you haven't solved the problem. You've just moved the debt.
Paying for Education
Home equity may also be an option for education expenses.
But this is where I’d want to compare the actual numbers.
What would student loans look like?
What would accessing your equity look like?
What are the interest rates, payments, fees and repayment terms?
Put the options next to each other and see which one makes the most sense for your situation.
Helping a Family Member Buy a Home
Maybe you've owned your home for 15 or 20 years and have built substantial equity.
Meanwhile, your kids are trying to buy their first home.
Some homeowners choose to access part of their equity to help a child or family member with a down payment.
That can be a really meaningful use of the wealth you've built through homeownership.
But I wouldn't want someone putting their own financial stability or retirement at risk just so someone else can buy a house sooner.
The numbers still need to make sense for you.
Handling a Major Financial Emergency
Life happens.
Job loss. Major unexpected expenses. Something breaks. A situation comes up that you simply weren't planning for.
If the alternatives are things like high-interest credit cards or pulling money from retirement accounts, accessing your home equity may be one option worth comparing.
The key word is comparing.
Don't assume home equity is automatically the best answer.
Look at all of your options and understand what each one costs before making the decision.
What Should I Be Careful With Using Home Equity For?
There are also situations where I'd slow down before borrowing against your house.
Vacations, Cars and Lifestyle Purchases
Can you use home equity for these things?
Potentially.
But remember what you're doing.
You're borrowing money against your house.
That doesn't automatically make the purchase wrong, but I'd ask whether whatever you're buying is worth putting your home behind the debt.
Investing the Money
Borrowing against your house to invest adds another layer of risk.
Investments can go down.
Your loan payment doesn't.
There may be situations where someone decides that risk makes sense, but you should understand exactly what you're taking on before using your home as collateral for an investment strategy.
Funding a Business
I'm all for entrepreneurship.
But businesses don't always work out the way we expect.
If you're considering borrowing against your home to fund a business, ask yourself a very simple question:
If this business makes $0, can I still comfortably afford the payment?
If the entire plan depends on the business succeeding, you're taking on a much different level of risk.
Covering Your Normal Monthly Expenses
This is probably the biggest warning sign.
If you're consistently short every month and you're considering tapping your equity to cover the difference, accessing your equity might temporarily relieve the pressure.
But it doesn't necessarily fix the underlying problem.
If you're short $1,000 every month, eventually the borrowed money runs out and that $1,000 problem is still there.
I'd want to figure out what's causing the monthly shortfall first.
How Do I Actually Access My Home Equity?
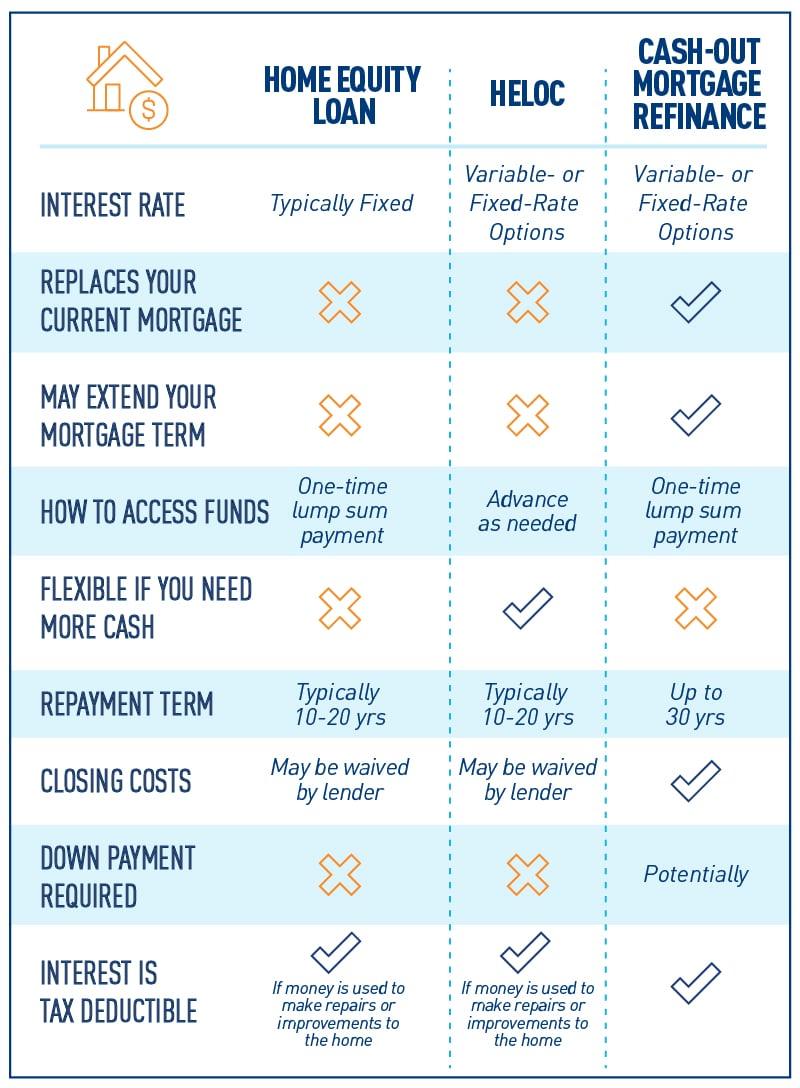
Once you know why you want the money, then we can talk about how to access it.
There are three common options.
HELOC
A Home Equity Line of Credit, or HELOC, is a revolving line of credit secured by your home.
Think of it almost like having a bucket of money available.
If you're approved for a $100,000 line, you don't necessarily have to pull out the entire $100,000 immediately. You can generally access money as needed during the draw period, subject to the terms of the HELOC.
Your existing first mortgage stays in place.
This can be useful for something like a renovation where you're going to need money at different stages rather than all at once.
HELOC rates are commonly variable, so that's something you'll want to understand before moving forward.
Home Equity Loan
A home equity loan works a little differently.
Instead of having a revolving line available, you're generally borrowing a specific lump sum.
Maybe you know:
“I need $75,000.”
You receive the funds and repay the home equity loan separately from your existing mortgage.
This can make sense when you know approximately how much money you need and want a more predictable repayment structure.
Your existing first mortgage also stays in place.
Cash-Out Refinance
A cash-out refinance is different because you're replacing your existing mortgage.
Let's say you owe $500,000 on your house and have substantial equity.
Instead of keeping that $500,000 mortgage and adding another loan, you could potentially refinance into a larger mortgage and receive a portion of the difference in cash.
But there's one big thing I'd want to look at:
What's the interest rate on your existing mortgage?
If you currently have a very low mortgage rate, replacing that entire loan with a new mortgage at today's rate just to access some cash may or may not make sense.
That's why I don't think homeowners should automatically assume:
“I need cash, so I should refinance.”
Maybe.
But maybe keeping your existing mortgage and using a HELOC or home equity loan makes more sense.
We need to actually run the numbers.
Which Home Equity Option Is Best?
There isn't one answer that works for everybody.
Generally, I'd start by asking:
How much money do you need?
Do you need it all at once or over time?
What is your current mortgage rate?
How long do you expect to carry the new debt?
What are you using the money for?
What will the new monthly payment look like?
Those answers help determine whether a HELOC, home equity loan, cash-out refinance—or simply leaving your equity alone—makes the most sense.
So, Should I Use My Home Equity?
Here's the simplest way I think about it:
Don't start with the loan. Start with the goal.
What are you trying to accomplish?
How much money do you actually need?
What options do you have?
What does each option cost?
And most importantly:
Does doing this leave you in a better financial position than doing nothing?
Sometimes the answer will be yes.
Sometimes the smartest move is leaving your equity exactly where it is.
And sometimes we need to put a HELOC, home equity loan and cash-out refinance next to each other and actually see what the numbers look like.
That's the part I can help with.
If you're a California homeowner wondering how much equity you have or what accessing it could look like, reach out.
We can look at your current mortgage, what you're trying to accomplish and the options available to you.
Then you can decide what makes the most sense.
No guessing. Just the numbers and a plan.
Need More Help?
Sometimes a quick answer isn't enough. Our guides, checklists and toolkits help you actually get it done.
Can't Find What You're Looking For?
Send in your question and tell us what you're trying to figure out.
Practical knowledge for everyday life.
Explore
StoryClip Media
©2026 . All Rights Reserved | Privacy Policy | Terms of Service